Payroll is how a business pays its employees and handles the taxes on their wages. Each pay period, you count the hours worked, take out taxes and other deductions, pay your team, send the taxes to the government, and record everything in your books. That may sound like a simple paycheck job, but it is more than that. Payroll touches your taxes, your records, and your cash flow. One mistake can mean an unhappy employee or a penalty from the IRS.
This guide explains how payroll processing works in plain words. You will see each step, the taxes you owe, a real pay example with numbers, and what payroll costs.
What Is Payroll for a Small Business?
For a small business, payroll is the process of calculating what employees have earned, paying them, withholding the right taxes, and recording those payments correctly. Even with only one or a few employees, the business still has payroll tax and reporting responsibilities.
Each pay period, you need to know how much each employee earned, what should be taken out for taxes and other deductions, and how much the employee should receive. You also need to set aside and send payroll taxes to the government and keep accurate payroll records.
A few terms make the process easier to understand. Gross pay is what an employee earns before anything is taken out. Net pay is what reaches the employee after taxes and deductions. Withholding is money taken from the employee’s pay and sent to the government on their behalf.
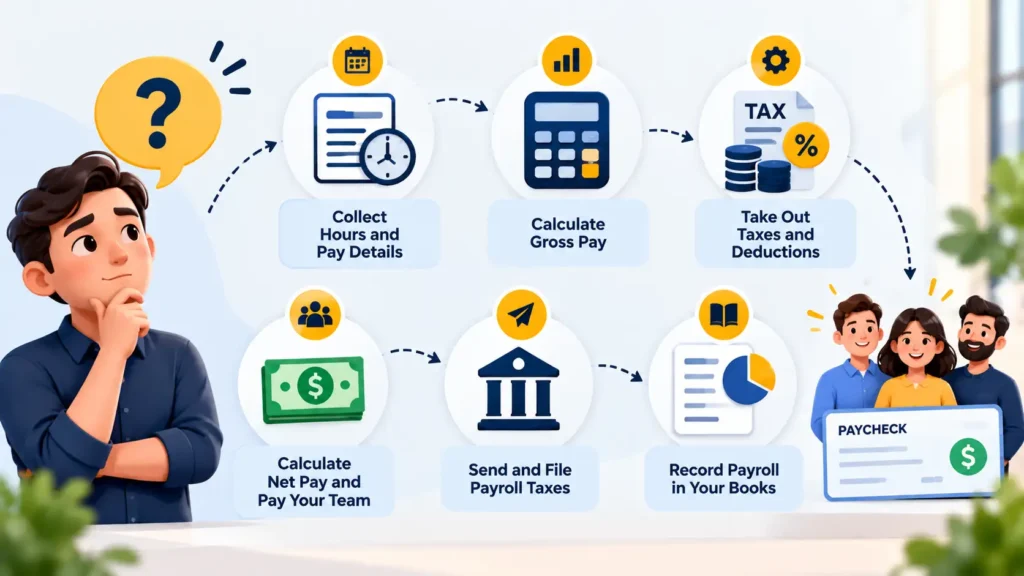
How Does Payroll Work? The 6-Step Payroll Cycle
Every payroll follows the same basic cycle. The details change from business to business, but the steps stay the same.
Step 1: Collect Hours and Pay Details
Start by gathering what you need for the pay period. For hourly workers, that means hours worked, overtime, and paid time off. For salaried workers, check for changes like a raise or a bonus. Also look for new hires, people who left, and any change to deductions.
Step 2: Calculate Gross Pay
For hourly employees, multiply the hours worked by the pay rate. Most hourly workers must be paid at least one and a half times their regular rate for hours over 40 in a week. For salaried employees, divide the yearly salary by the number of pay periods in the year.
Step 3: Take Out Taxes and Deductions
Next, subtract the amounts that must come out of pay. These include federal income tax, Social Security tax, and Medicare tax. Some states and cities have their own income taxes too. You may also take out things like health insurance or retirement contributions. The next section explains each tax.
Step 4: Calculate Net Pay and Pay Your Team
Gross pay minus taxes and deductions equals net pay. Then you pay your employees, most often by direct deposit or paper check. How fast the money arrives depends on your payroll provider and your bank.
Step 5: Send and File Payroll Taxes
The money you take out of paychecks is not yours to keep. You must send it to the IRS, along with your own share of payroll taxes, on a set schedule. You also file tax forms during the year. The dates are covered later in this guide.
Step 6: Record Payroll in Your Books
Finally, record the payroll. Wages, employer taxes, and the amounts you still need to pay to the government all need to go into the right accounts. Keep pay slips, payroll reports, and proof of tax payments. Good records make it easy to answer questions from employees, your accountant, or the IRS.
What You Need Before Your First Payroll
A little setup work makes every payroll after that easier.
Get an EIN and Register With Your State
An Employer Identification Number, or EIN, is a number the IRS gives your business. You need one to report payroll taxes. You may also need to register with your state for withholding and unemployment taxes. The rules are different in each state, so check with your state tax agency.
Collect Forms From Each New Employee
Every new employee fills out a Form W-4, which tells you how much federal income tax to withhold. They also complete a Form I-9, which proves they can legally work in the United States. Employers also have to report new hires to their state.
Know Who Is an Employee and Who Is a Contractor
Employees go on payroll. Independent contractors do not. The difference depends on how much control you have over the work, not on what you call the person. If you label a worker a contractor when the person should be an employee, you may have to pay back taxes and penalties. When you are not sure, ask an accountant before you decide.
Pick a Pay Schedule
The most common schedules are weekly, every two weeks, twice a month, and once a month. Weekly and biweekly are common for hourly teams. Some states have rules about how often you must pay, so check your state’s law before you choose.
Payroll Taxes Explained
Payroll taxes confuse many owners because some are paid by the employee and some by the employer. Here is how they split. The figures below are for 2026 and come from the IRS Employer’s Tax Guide, Publication 15.
Taxes Taken From the Employee’s Pay
Federal income tax is taken from each paycheck based on what the employee wrote on the W-4. The amount is different for each person. Social Security tax is 6.2% of pay. It only applies to the first $184,500 an employee earns in 2026. After that, no more Social Security tax is taken for the year. Medicare tax is 1.45% of pay. There is no earnings limit for Medicare tax.
Taxes the Employer Pays
As the employer, you pay a matching 6.2% for Social Security and a matching 1.45% for Medicare. That is on top of the employee’s share, so the total is 7.65% from you and 7.65% from the employee.
You also pay federal unemployment tax, called FUTA. The FUTA rate is 6.0% on the first $7,000 you pay each employee in a year. Most employers get a credit of up to 5.4% when they pay their state unemployment tax on time. That brings the real rate down to 0.6%, which is a maximum of $42 per employee per year.
State unemployment tax is the third piece. The rate and the wage limit depend on your state and on your business, so look up your own numbers with your state agency.
Payroll Example: From Gross Pay to Net Pay
Let’s walk through one paycheck. Say you have an hourly employee who earns $20 an hour. You pay every two weeks, and she worked 80 hours. Her gross pay is $20 times 80 hours, which is $1,600.
From that, you take out the Social Security tax of 6.2%, which is $99.20. You take out Medicare tax of 1.45%, which is $23.20. Together, that is $122.40 in FICA taxes. Now say her W-4 leads to $120 in federal income tax. That number changes from person to person, so we are using $120 only to keep the example simple.
Her net pay is $1,600 minus $122.40 minus $120. That is $1,357.60. You are not done yet. As the employer, you must pay a matching $122.40 in Social Security and Medicare tax. So this one paycheck costs you $1,722.40, before FUTA, state unemployment tax, and any benefits.
The IRS also needs its share. For this paycheck, you will send the IRS $364.80. That is her $120 in income tax, her $122.40 in FICA, and your matching $122.40.
What Payroll Really Costs a Small Business
Most owners think of payroll as wages. The real cost is higher.
Using the same employee, 26 paychecks of $1,600 comes to $41,600 in wages for the year. Your matching Social Security and Medicare tax is 7.65% of that, which is $3,182.40. FUTA adds up to $42. That puts your yearly cost at about $44,824.40 for one person. And that is not the full picture. State unemployment tax, workers’ compensation insurance, health benefits, paid time off, and payroll software or service fees all come on top. Add these when you set prices and plan your budget.
Payroll Deadlines and Filings
Missing a payroll tax date costs real money, so it helps to know the calendar.
When to Deposit Payroll Taxes
The IRS puts you on a deposit schedule, either monthly or semiweekly. It looks at how much payroll tax you reported in a past 12-month period, called the lookback period. If you reported $50,000 or less, you are a monthly depositor. If you reported more than $50,000, you are a semiweekly depositor. New employers start as monthly depositors.A monthly depositor sends the taxes for one month by the 15th of the next month. A semiweekly depositor sends taxes a few days after each payday, based on the day of the week the pay was given.
There is one rule that overrides both. If your unpaid payroll taxes reach $100,000 on any day, you must deposit them by the next business day. You can read the full rules in IRS Notice 931.
Forms You File
Form 941 is filed every quarter. It reports the income tax you withheld and the Social Security and Medicare taxes. It is due on the last day of the month after the quarter ends, so the dates are April 30, July 31, October 31, and January 31.
Form 940 is filed once a year and reports FUTA tax. It is due January 31. You also give each employee a Form W-2 by January 31. It shows what you paid them and what you withheld during the year.
What Happens if You Are Late
Late deposits come with penalties. The penalty is 2% of the unpaid amount if you are 1 to 5 days late. It is 5% if you are 6 to 15 days late and 10% if you are more than 15 days late. If you still have not paid 10 days after the IRS sends a notice, it rises to 15%.
How Payroll Affects Your Bookkeeping and Cash Flow
Every payroll changes your books. Let’s use the same paycheck again.
You record $1,600 as wage expense and $122.40 as employer payroll tax expense. The $1,357.60 you pay the employee leaves your bank account on payday. The other $364.80 stays in your account for now, but it is a bill you owe the IRS. Your bookkeeping records show it as a payroll tax liability until you deposit it.
This is where cash flow management comes in. Payroll takes cash twice. First on payday, and again when the tax deposit is due. If you do not set money aside for taxes, a deposit date can catch you short. A simple habit helps: move the tax amount into a separate account each payday. It is also smart to check your payroll report against your bank statement each month. If the numbers do not match, you want to find out early.
What Changes With More Than One Location or State?
Payroll gets harder as you grow. Each state has its own income tax rules and its own unemployment tax. If your employees work in more than one state, you may need to register in each one.
With more than one location, you also want to know what each location pays in labor. That means tagging every paycheck to the right place.
DIY, Payroll Software, PEO, or Outsourced Payroll: Which Is Right for You?
There are four common ways to run payroll. Doing it yourself means calculating everything by hand or with a spreadsheet. It costs the least, but you carry all the work and all the risk. It can work for one or two employees, if you are careful.
Payroll software does the math, pays your team, and often files your taxes. You still enter the hours and review the results. It suits owners who want to stay hands-on without doing the calculations.
A PEO, which is a professional employer organization, shares some employer duties with you, such as payroll, benefits, and HR. It can help if you want one company to handle many things, but you give up some control.
Outsourced payroll means a firm like an accountant or a bookkeeping company runs it for you. This fits best when payroll is taking too much time, you have more than one location, or you want your payroll tied to your books.
A good sign that it is time to outsource is when payroll keeps getting pushed to the last minute, or when you have made a tax mistake. At that point, the fee is often cheaper than the cost of fixing errors.
5 Common Payroll Mistakes and How to Avoid Them
Payroll mistakes often start small, like a wrong tax rate or a missed deadline. Left alone, they can lead to IRS penalties and unhappy employees. Here are five common ones and a simple way to avoid each.
1. Mixing Up Employees and Contractors
Calling a worker a contractor does not make it true. If the IRS decides the person was an employee, you can owe taxes and penalties. Learn the rules before you hire, and ask a professional if you are unsure.
2. Paying Taxes Late
Late deposits bring penalties of 2% to 15%. Put every deposit date on a calendar, or let your payroll provider handle it.
3. Keeping Poor Records
Missing time records and wrong pay rates cause pay errors. Keep timecards, pay slips, and tax confirmations for each pay period, and check them before you approve payroll.
4. Using Old Tax Numbers
Tax rates and wage limits change. The Social Security limit went from $176,100 in 2025 to $184,500 in 2026. If you run payroll by hand, update your numbers every January.
5. Skipping the Review Before Payday
A quick review catches odd hours, wrong rates, and missed overtime. It is much easier to fix a mistake before the money goes out than after.
Conclusion
Payroll comes down to six steps: collect hours, calculate gross pay, take out taxes, pay your team, send and file taxes, and record it all. The hard part is doing it the same way, on time, every pay period.
Know your taxes, mark your deadlines, and set aside cash for tax deposits. Check your numbers before each payday, and keep good records. If payroll starts to take too much time, getting help is a smart move.
Need Help Managing Payroll and Bookkeeping?
Payroll affects your employees, your taxes, your cash flow, and your books. BeanSquad in Westport, CT helps businesses keep all of this organized so you can focus on running your business.
If payroll is taking too much of your time, we can help. Schedule a free consultation to talk about your needs.
Frequently Asked Questions
How does payroll work for a business with one employee?
The steps are the same as for a large team. You calculate pay, take out taxes, pay the employee, send the taxes, and keep records. You still need an EIN and a W-4 from the employee.
Do I need an EIN to run payroll?
Yes. You need an EIN to report payroll taxes to the IRS, and it goes on forms like Form 941 and Form W-2. You can apply for one for free on the IRS website, so get it before you hire your first employee.
What is the difference between gross pay and net pay?
Gross pay is what an employee earns before taxes and deductions. Net pay is the amount the employee takes home after those are taken out.
How often should a small business run payroll?
The most common choices are weekly, every two weeks, twice a month, or monthly. Pick one that works for your cash flow, and check your state’s rules before you decide.
Can I run payroll myself?
Yes, many owners do, especially with a small team. You must calculate pay and taxes correctly and meet every deposit and filing date. If that feels like too much, software or an outside provider can help.
What payroll taxes do employers pay?
Employers pay a matching 6.2% Social Security tax and a matching 1.45% Medicare tax. They also pay federal unemployment tax and state unemployment tax. Employees pay the other half of Social Security and Medicare, plus federal income tax.