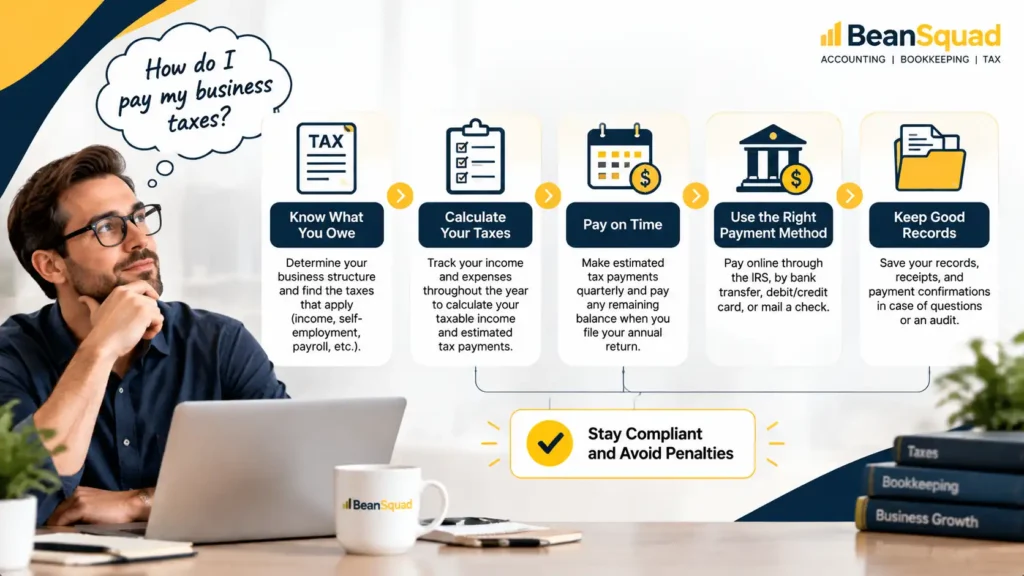
Small business owners pay federal taxes through IRS payment systems and pay applicable state and local taxes through the relevant tax agencies. Depending on the business’s tax classification, the owner may pay income tax personally, the company may pay it, or both may have separate obligations. Estimated payments and payroll deposits can fall due before annual returns.
For franchise owners, the process starts with identifying the taxpayer behind each location. Confirm the taxes that apply, calculate the amount using current records, choose an accepted payment method, and select the correct tax period. A new location does not automatically mean a separate federal income tax return.
BeanSquad, based in Westport, Connecticut, supports franchise owners with bookkeeping and tax preparation coordination. Whether you operate one unit or several, keep business tax payments, personal estimated taxes, and amounts collected from customers or withheld from employees clearly identified.
Identify How Your Franchise Business Is Taxed
Your franchise brand does not determine your federal tax classification. Start with the entity’s formation documents, tax elections, and previous returns.
| Tax classification | Typical federal income tax reporting | Who generally pays the income tax? |
| Sole proprietor | Reports business profit or loss on Schedule C with the individual return | The owner |
| Partnership | Files Form 1065 and provides Schedule K-1 information to partners | Partners generally report their shares on their own returns |
| S corporation | Files Form 1120-S and provides Schedule K-1 information to shareholders | Shareholders generally pay tax on pass-through income, with certain entity-level exceptions |
| C corporation | Files Form 1120 | The corporation pays tax on its taxable income. Shareholders may also owe tax on dividends |
These are common federal arrangements. State treatment can differ. The IRS provides separate guidance for sole proprietorships, partnerships, S corporations, and corporations.
An LLC does not have one fixed federal tax treatment. Depending on ownership and elections, the IRS may treat it as a disregarded entity, partnership, or corporation. A single-member LLC can also be separate from its owner for employment tax purposes even when it is disregarded for income tax.
For a multi-unit franchise, identify which entity operates each location before deciding how to file or pay. Store-level reports help organize the numbers, but the tax classification determines how those numbers feed into returns.
Determine Which Taxes You Need to Pay or Remit
A franchise’s tax responsibilities can involve its profits, employees, transactions, property, and business activities. Not every tax below applies to every operation.
| Tax or obligation | When it may apply | Who pays or remits it? |
| Federal and state income tax | Taxable income, depending on classification and jurisdiction | The owner or entity |
| Self-employment tax | An individual’s qualifying net earnings from self-employment | The individual |
| Employment taxes | Wages paid to employees | The employer remits withholding and applicable employer taxes |
| Sales and use tax | Taxable sales or purchases under state and local rules | The seller may collect and remit sales tax. The purchaser may owe use tax |
| Franchise or gross receipts tax | Business activity or entity status in a jurisdiction imposing it | The liable business |
| Property tax | Taxable real estate or business property under local rules | The liable owner or business |
| Excise tax | Certain products, services, equipment, or activities | The person or business specified by the applicable rules |
The IRS business tax overview explains the federal categories. State and local requirements need their own review.
Keep the accounting distinction clear. Employee withholding and customer sales-tax collections are amounts to account for and remit. Do not treat them as spare cash for another location’s operating expenses.
Also, a government-imposed franchise tax is different from a fee or royalty paid to your franchisor. The shared word “franchise” does not make them the same obligation.
Prepare Your Records and Calculate What You Owe
Start with reconciled records for the entity making the payment. A combined sales total from every location is not enough to calculate every tax.
For the review, gather:
- Income statements and balance sheets for each entity.
- Sales, refunds, and sales-tax reports by location.
- Payroll reports and previous tax deposits.
- Expense records, franchise agreements, and royalty statements.
- Equipment purchases and new-location costs.
- Prior returns, estimated payments, credits carried forward, and tax notices.
For income tax planning, your tax professional may need to adjust accounting profit for tax treatment. Rent, payroll, and other operating expenses need supporting records. Initial franchise costs and equipment purchases may require different treatment from recurring expenses.
The IRS explains the ordinary-and-necessary expense standard in Publication 583. Its business expense resource guide directs readers to guidance on specific costs. Avoid assuming every payment your franchise makes creates an immediate deduction.
For an owner’s estimated income tax, include relevant personal tax information as well as franchise income. Other income, withholding, deductions, and credits can affect the amount due.
Use a calculated forecast rather than a universal percentage of sales. Update it when profits change or another location opens. If the supporting records are inconsistent, first address how you manage bookkeeping across multiple franchise locations.
Choose the Correct Tax Payment Method
The correct payment route depends on whether you are paying an individual liability, a business liability, or a required deposit.
How to Pay Federal Business Taxes
Start at the official IRS payments page. Current bank-payment options include:
| Payment option | How it can help |
| Business Tax Account | Eligible users can make supported business payments and review account information |
| Direct Pay for businesses | Makes supported business payments from a bank account without signing in |
| Electronic Federal Tax Payment System, or EFTPS | Supports federal tax payments, including recurring payments |
Check that the selected service accepts your tax and payment type. For required federal tax deposits, follow the electronic-deposit rules rather than assuming another payment method is interchangeable.
Prepare the entity’s taxpayer identification details, tax form or payment category, tax period, amount, and bank information before starting. If you manage several franchise entities, confirm you are using the details for the one that owes the tax.
How Owners Make Estimated Tax Payments
An owner paying individual estimated income tax can use an IRS Individual Account or Direct Pay for individual taxes. The IRS also permits other methods, including mailing a payment with the appropriate Form 1040-ES voucher.
Select estimated tax and the intended tax year when making the payment. Do not assume a payment under the franchise company’s EIN will satisfy a personal obligation.
Individuals generally use Form 1040-ES to calculate estimated tax. Use the current instructions and confirm how prior payments and withholding affect the remaining amount.
How to Pay State and Local Taxes
Use the relevant state or local agency’s official payment system and instructions. An IRS payment does not settle a separate state tax bill.
For each franchise entity, confirm the registration or account number, tax type, reporting period, and required payment method. Income tax, sales tax, and unemployment contributions may involve different accounts or agencies.
Keep access details organized so a manager’s departure does not leave the business unable to retrieve records or submit an upcoming payment.
How to Confirm Your Payment Was Applied Correctly
Save the confirmation and record the amount, tax period, payment date, and taxpayer. Then match the bank withdrawal to the payment record.
Where account history is available, check that the tax agency recorded the payment against the intended obligation. A bank withdrawal alone does not tell your bookkeeping team which entity or period the payment belongs to.
Follow the Right Payment and Filing Schedules
Filing a return reports tax information. Making a payment or deposit transfers money toward the obligation. Those deadlines can be different.
Estimated Tax Payments
Individuals, including sole proprietors, partners, and S corporation shareholders, generally need estimated payments when they expect to owe at least $1,000 on filing. Exceptions apply, including situations involving sufficient withholding.
For calendar-year individuals, the usual federal estimated-payment schedule is:
| Income period | Usual payment deadline |
| January through March | April 15 |
| April through May | June 15 |
| June through August | September 15 |
| September through December | January 15 of the following year |
Weekend, holiday, disaster-relief, and other applicable rules can change deadlines. Check the IRS estimated-tax due dates. Corporate and fiscal-year schedules require separate review.
Although people call them quarterly payments, the income periods are not four equal three-month blocks. Seasonal franchise owners should discuss uneven income with their tax professional rather than assuming identical installments fit every situation.
Payroll Deposits and Returns
Do not wait for a quarterly payroll return to make deposits that are due earlier. The IRS generally uses monthly or semiweekly deposit schedules for federal income tax withholding and Social Security and Medicare taxes, with special rules that can require faster deposits. FUTA has separate requirements.
Check the IRS employment-tax deposit guidance. If a provider handles your franchise payroll, confirm who schedules deposits, verifies completion, and follows up on notices.
State and Local Deadlines
Use each agency’s assigned schedule. Do not copy the filing frequency from one franchise location to another without checking it.
Maintain a tracker with these fields:
| Field | What to record |
| Taxpayer | Legal name and relevant account identifier |
| Jurisdiction and tax | Agency, tax type, and reporting period |
| Filing deadline | When the return must be submitted |
| Payment deadline | When the payment or deposit is due |
| Responsibility | Who prepares, approves, and submits |
| Completion | Filing receipt and payment confirmation |
Coordinate Tax Payments Across Franchise Locations
Centralize oversight while keeping the underlying entity and location records clear. A shared tracker helps, but each payment still needs the correct taxpayer and account details.
If employees, sales channels, inventory, or locations expand into another state, review the tax implications before relying on the existing setup. Different taxes can require different jurisdictional analyses.
BeanSquad’s guide to sales tax nexus for multi-location franchises explains how business activity can create sales-tax responsibilities. Keep that review connected to expansion decisions.
Assign someone to collect notices from every location and route them to the person responsible for that entity’s taxes. Ask for completion records when an outside provider handles filings or payments. This creates a clear handoff between the operator, bookkeeping team, and tax professional.
Check These Details Before Submitting a Tax Payment
Before approving the payment, confirm:
- Taxpayer: Does the name and identification number match the liability?
- Tax type: Is this an estimated payment, deposit, return balance, or notice payment?
- Period: Have you selected the correct year or reporting period?
- Amount: Does it match the reviewed calculation?
- Bank details: Is the account authorized and adequately funded?
- Timing: Will the chosen method meet the required deadline?
- Duplication: Has an owner, payroll provider, or accountant already scheduled it?
- Evidence: Who will retain the confirmation and verify completion?
Use the same review across your franchise operation, including when someone covers another team member’s responsibilities.
Frequently Asked Questions
Can I Pay My Business Taxes From a Personal Bank Account?
Check the payment service’s account-authorization requirements and confirm how the transaction should be recorded. For franchise accounting, using an account aligned with the taxpayer makes reconciliation clearer.
If personal funds cover an entity obligation, ask your accountant how to record the funding. The bank account used does not determine whether a tax is a business expense or an owner’s personal liability.
What If I Cannot Pay the Full Amount?
File required returns on time, pay what you can, and review the applicable agency’s payment options promptly. The IRS offers payment plans, subject to eligibility and terms. Interest and applicable penalties can continue. If several franchise entities owe money, identify each liability separately before requesting an arrangement. A federal agreement does not resolve separate state obligations.
Do I Still Have Tax Obligations If My Franchise Makes a Loss?
Possibly. A loss does not automatically eliminate return requirements, employment taxes, sales-tax remittance, or applicable state and local obligations. Review the tax involved and the entity’s circumstances. One location’s accounting loss also does not establish the tax position of the entire business.
Does My Franchisor Pay Taxes on My Behalf?
Do not assume so. Review the franchise agreement and any specific service arrangements. Franchisor reporting and royalty payments are separate from the tax filings and payments your operating business may need to make.
Confirm who handles each obligation and obtain filing and payment records for work performed on your behalf.
Conclusion
Small business owners pay taxes by identifying who owes them, calculating the amount from current records, and using the correct federal, state, or local payment system. Estimated payments, payroll deposits, and return balances can follow different schedules.
For franchise owners, connect every payment to the right entity and tax period. Keep location records organized, review obligations when operations change, and retain confirmation of each payment. This makes it easier to see what has been paid and what still needs attention.
Start Planning Before Tax Season
Bring your franchise’s entity records, upcoming returns, and planning questions together before deadlines approach.
BeanSquad’s Tax Preparation & Planning service coordinates planning and the preparation of agreed business returns with qualified tax professionals. Schedule a free 30-minute consultation to discuss your franchise structure and tax preparation needs.